Understanding the economics and dynamics of the fragmented magnet industry requires acknowledging the hard work of the Chinese people who endured, persisted, and built the manufacturing ecosystem that exists today.
The current fragmented magnet industry is what happens when a society becomes overwhelmingly white-collar and the blue-collar role gets outsourced.
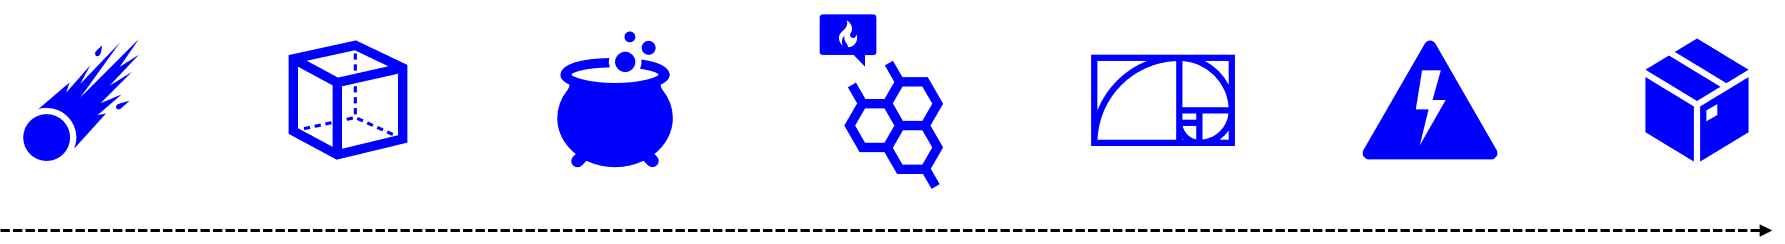
Look at the process below.
The end-stage manufacturing of Samarium Cobalt magnets is not exactly a guy pressing a button and waiting for a quarterly earnings report. It is a complex manufacturing process involving pressurization, fine jet milling, heat treatment, high-current magnetization, precision machining, inspection, and packaging extremely delicate and fragile magnets.
Like manufacturing hardware for aerospace, it is an exercise in balancing materials science, manufacturing science, process control, and experience.
It is not something where keyboard warriors can invent a supply chain overnight, slap a valuation on it, and call it a day.
We believe we are well positioned to participate in what comes next in the magnetic materials industry.
We have partnered with manufacturers and suppliers capable of helping us meet the DFARS requirements taking effect in January 2027, which require both origin and manufacturing to be outside of China.
We spent years developing relationships with small, lean, results-driven partners capable of doing this.
We stayed under the radar. We kept our heads down.
We started by trading raw materials available on the open market. Then we moved closer to the mining and processing side of the business. We learned what it takes to go from a lot of dirt to a usable material, from material to alloy, and from alloy to an actual magnet that a customer can put into an assembly.
Most importantly, we learned the unit economics.
So let us tell you about why we are all in for another grift.
If we look at the chart below, we can see exports under HS classification 850511 — permanent magnets and articles intended to become permanent magnets — by country in 2024.
This data predates the latest export restrictions.
The cumulative industry represented approximately $5.5 billion in exports under this classification.1
For a product category with a PCI index of approximately 0.43, we can make a simple thought experiment.
Imagine a fictitious company controlling a meaningful portion of this industry. You could argue that such a business deserves a valuation somewhere between an industrial hardware company such as Moog and a mature product category with significant demand but limited structural growth.
Magnets are, after all, still a cost-sensitive business.
Let's be generous.
Let's use a 3× price-to-sales multiple.
$5.5 billion × 3 = $16.5 billion
Congratulations
We have just created a $16.5 billion company.
And this is where things get interesting.
Because some of the largest companies being valued against this opportunity are approaching that scale before necessarily demonstrating the corresponding downstream magnet production, customer penetration, or fully integrated supply chain.
The market is effectively asking investors to price the outcome before the manufacturing ecosystem has been built.
That's an interesting trade.
But we're still talking amount mining.
Here's the part that gets lost in the PowerPoint presentations.
Mining is not the magnet business.
Even successfully producing the raw material does not mean you have solved the supply chain.
A significant portion of the material still needs to be refined, separated, processed, converted into usable alloy, manufactured into magnets, machined to customer specifications, magnetized, inspected, packaged, and delivered.
And then you have to find someone willing to buy it.
Some companies are effectively modeling a world where, once the material is successfully refined, utilization will be close to 100% and a massive backlog of demand will simply be waiting for them.
Maybe.
But the pre-restriction magnet market gives us another data point.
Magnet manufacturers competed for customers.
They competed on price.
US resellers competed on price.
And increasingly, some of the industry moved toward an e-commerce model.
That is not exactly the behavior of a market where customers will pay whatever you want because the product is strategically important.
Here's the uncomfortable part.
A substantial portion of the US magnet supply chain has historically consisted of Chinese magnets being imported, marked up, and sold through US intermediaries.
In other words, the customer wasn't necessarily buying an exotic strategic material.
They were buying a commodity-like industrial component with several layers of margin attached to it.
In some cases, the underlying magnet could represent only a fraction of the final selling price.
This tells us something important about demand.
The demand for magnets is real.
But the willingness to pay is not unlimited.
Why?
Because high-temperature and high-performance magnets are often engineering solutions to very specific constraints.
They allow engineers to reduce the size, weight, complexity, or mechanical components required in an assembly.
That makes them extremely valuable to the engineer.
But it does not necessarily make the magnet itself infinitely valuable.
In many applications, the magnet is a very small component inside a much larger system.
And that creates an economic ceiling.
Permanent magnets are often a product of engineering convenience rather than absolute necessity.
That distinction matters.
You cannot simply charge $50 for a 1 × 1 × 1 cm magnet because the material is strategically important and expect the customer to smile and hand you the money.
The customer has a budget.
The engineer has alternatives.
The procurement department has a spreadsheet.
And everyone has a competitor.
Our customers are already negotiating over magnets that are approximately 1 × 1 × 0.2 cm.
The current price can be around $0.78 per piece, and they still want it lower.
Think about that.
We are talking about a technically sophisticated material being produced through a complicated manufacturing process, sold as a tiny component, with customers still negotiating over cents.
This is not a gemstone business.
There is a ceiling to what the market will pay for the physical magnet.
You can employ people in India, Malaysia, Pakistan, or elsewhere to manufacture magnets.
That does not solve the fundamental problem.
If the objective is to rebuild a domestic or allied supply chain, labor is only one component.
First, you need feedstock.
Then you need refining.
Then separation.
Then alloy production.
Then powder processing.
Then pressing.
Then sintering and heat treatment.
Then machining.
Then magnetization.
Then inspection.
Then packaging.
Then logistics.
Every step introduces cost, yield loss, capital requirements, quality-control requirements, and another opportunity for something to go wrong.
Historically, much of this ecosystem benefited from lower-cost feedstock, lower operating costs, established industrial infrastructure, and a supply chain denominated largely in RMB.
Now imagine rebuilding the same system using Australian and American material, higher labor costs, higher regulatory costs, higher overhead, and inputs denominated in USD or AUD.
The economics change.
And they change before the first magnet ever reaches the customer.
This is where the PowerPoint gets even more interesting.
The government can subsidize magnet production on a per-kilogram basis.
Great.
But what happens when your customer wants a complicated magnet with a low manufacturing yield?
You don't get paid for the magnet that cracked.
You don't get paid for the powder that was lost.
You don't get paid for the machining operation that produced a rejected part.
You get paid for the product that made it through the process.
So now you have a low-margin product, a complicated manufacturing process, expensive feedstock, expensive labor, and potentially significant yield loss.
And someone still wants you to lower the price.
Do the math.
You are taking a magnet that is already a relatively low-margin industrial product in China, moving the supply chain into higher-cost jurisdictions, increasing the cost of raw materials and labor, and somehow expecting the finished product to become cheaper because Silicon Valley tech bros are going to automate everything and AI the problem away.
That will probably happen.
After we get AGI and GTA 6.
And then there is one more problem.
China is still keeping much of the neodymium magnet supply flowing.
The restrictions are not equivalent across every magnet material.
Samarium Cobalt is a much smaller market than the headline permanent-magnet market would suggest.
That matters enormously when investors start taking a broad permanent-magnet market number and applying it directly to a specific material.
You can end up with a situation where a company is being valued on the theoretical future of a market that is substantially smaller than the headline number being used to justify the valuation.
So let's go back to our $5.5 billion figure.
If that is the total 2024 export value under HS 850511, then a 3× sales multiple produces a hypothetical $16.5 billion valuation.
But that $5.5 billion includes a much broader category than Samarium Cobalt.
So the actual addressable market for the specific thesis can be materially smaller. As the market value for the specific type of export restriction only applies to HS 8505.11.90, not 8505.11 as a whole category.
Which means the valuation exercise gets even more interesting. As the sales pie now is significantly smaller.
Put differently, the market is effectively assigning a $16.5 billion valuation to a sector generating roughly $1.1 billion in revenue potential, when the market capitalization should be of $3.3 billion (based on a P/S of 3x).
We're effectively asking investors to pay today for:
**What if we successfully mine it?**
**What if we successfully refine it?**
**What if we successfully turn it into alloy?**
**What if we successfully manufacture magnets?**
**What if the yield is good?**
**What if customers accept the price?**
**What if demand materializes?**
**What if the supply chain works?**
**What if competitors don't undercut us?**
**What if the subsidies continue?**
**What if the economics eventually work?**
That's a lot of "what ifs."
And somewhere along the way, someone put a very large number on the PowerPoint.
This gets even funnier when you look at Arnold Magnets, operating under Compass Diversified’s portfolio. Arnold reportedly generates only around $100 million in annual revenue, despite being a legacy supplier to the defense and aerospace industries. And yet the entire Compass Diversified package carries a market capitalization of roughly $3 billion. A valuation that includes Arnold alongside a collection of other PortCo businesses.
Good luck.
And have fun investing.
1According to World Bank WITS trade data, global 2024 imports under HS 850511